14 July 2026
Chancellor set to announce financial services skills agreement
- More than 20 major financial services firms sign ‘once in a generation’ skills agreement between government and the sector
- Signatories agree to upskilling staff, new talent development, and annual reporting on progress
- Firms collectively employing more than 250,000 people have committed to the agreement
The Chancellor of the Exchequer will today announce that more than 20 financial services organisations have signed a pledge to invest in their own people, develop talent pipelines and collaborate to close the sector’s skills gaps.
As part of her annual Mansion House speech, the Chancellor will formally launch the Financial Services Skills Compact; a landmark, shared agreement between government, the Financial Services Skills Commission, and firms in the sector to work together to close skills gaps.
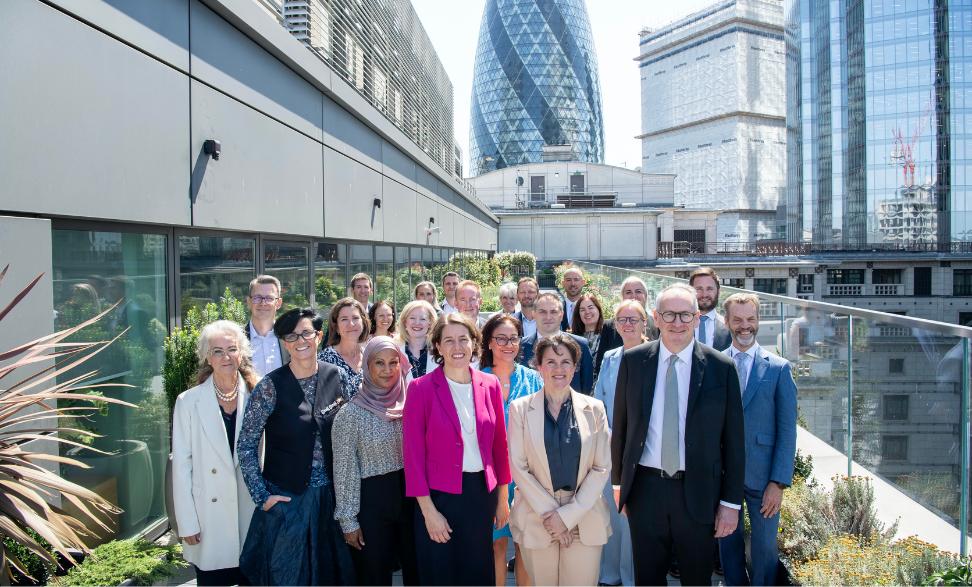
Twenty-two firms have formally signed the Skills Compact. They include high street banks, major insurers, building societies, investment managers, digital banks, and trade bodies, collectively employing more than 250,000 people.
The financial services sector employs around one million people across the UK and plays a vital role in driving economic growth. However, the sector is at a pivotal moment, amidst a rapidly evolving business environment.
Organisations face significant challenges driven by technological advancements, demographic change, and shifting customer expectations, all of which have been accelerated by the rapid adoption of artificial intelligence and other disruptive technologies.
In response to these challenges, the Skills Compact was announced by HM Treasury alongside the 2025 Financial Services Growth and Competitiveness Strategy. Its development has been led by the Financial Services Skills Commission and supported by City of London Corporation and TheCityUK.
Signatories to the Skills Compact have agreed to a range of commitments, including upskilling employees in AI and other critical skills, and growing structured routes for new talent. They will make a senior executive responsible for closing skills gaps and commit to publish annual updates on progress against their commitments.
Rachel Blake MP, Economic Secretary to the Treasury, said: “The Skills Compact is a central part of our ambitious plans to address skills gaps, including more investment in critical skills and getting more people into financial services.
“The backing of more than 20 organisations is a significant opportunity to deliver the workforce skills that are fundamental to the UK sector’s competitiveness, innovation and global leadership.”
Mark Hoban, Chair of the Financial Services Skills Commission, said: “Financial services is facing unprecedented disruption from AI and other technologies. Firms and the Government need to respond positively to this if the UK is to remain a world leading financial centre. We welcomed HM Treasury’s commitment last year to putting skills at the heart of the Competitiveness and Growth Strategy and today’s successful launch of the Skills Compact is the industry’s response to this challenge.”
Claire Tunley, Chief Executive of the Financial Services Skills Commission, said: “The Financial Services Skills Compact is the most significant agreement on skills between government and employers in a generation.
“The timing couldn’t be more important. The sector is at a pivotal moment; it needs to close skills gaps by focussing on upskilling and reskilling its own people, building a pipeline of new talent, and promoting a culture of continuous learning.
“These early signatories are taking the lead, embracing highly ambitious commitments that will benefit at least a quarter of a million employees. The fact that more than 25 organisations have already signed the Skills Compact, including some of the largest firms in the UK, signals the importance of skills to productivity and economic growth.”
Kate Bell, Assistant General Secretary at the TUC, said: “We welcome the launch of the Financial Services Skills Compact. The UK has long suffered from underinvestment in skills and training, so it is encouraging to see employers in financial services committing to invest in their workforce.
“AI is set to transform jobs across the economy, bringing huge opportunities but also significant challenges. Workers must be supported through this transition with access to high-quality training and opportunities to develop new skills.
“The most successful workplace training starts with listening to workers to understand their needs and co-design learning programmes. By working together, employers, government and unions can ensure that technological change improves jobs, boosts productivity and raises wages.”
Zareena Brown, Chief People Officer, Admiral Group: “At Admiral we are committed to investing in our people, supporting them to develop the critical skills needed to meet the evolving needs of our customers. It is the reason that so many of our colleagues have chosen to grow their career with us and has contributed to our success. We are proud to be the first signatory of the Skills Compact as we recognise that closing the skills gap in financial services requires collaboration. We look forward to working with HM Treasury, the Financial Services Skills Commission, and the wider industry to attract, develop and retain the talent that will drive the future success of our sector.”
Shilpa Shah, Head of Global Talent Acquisition & Skills, Barclays: “At Barclays, we believe that investing in people and skills is critical to our future success and to the long-term competitiveness of the UK’s financial services sector. The Financial Services Skills Compact provides an important opportunity for employers to work together to address evolving skills needs, accelerate capability building in areas such as AI, and create pathways for future talent. We are pleased to support this initiative and play our part in developing a workforce that is ready for the opportunities and challenges ahead.”
Julie-Ann Haines, Chief Executive Officer, Danske Bank UK: “We are delighted to be a signatory of the Skills Compact and to be investing in the future skills that our people need – from digital skills such as AI to adaptable, human centred skills. This Compact is an important opportunity for firms to work together, accelerate progress and ensure our industry has the skills it needs to thrive in a more AI augmented future.”
David Lindberg, UK Chief Executive Officer, HSBC: “As a founding member of the Financial Services Skills Commission, HSBC UK is delighted to underscore our commitment to building workforce skills that continue to meet our customers’ needs into the future. Signing the Skills Compact reinforces our focus on learning and attracting new talent, including through our excellent apprenticeship and graduate programmes.”
Emma Holden, Chief People Officer, L&G: “At L&G, we believe people are key to unlocking the opportunities created by technology and AI. Through working with partners across the industry to develop the skills our workforce needs to thrive in a changing world, the Financial Services Skills Compact will support innovation, growth and the long-term success of the UK financial services sector.”
Geraldine Kemp-Klotz, Chief People Officer, Leeds Building Society: “At Leeds Building Society, skills have always been at the heart of delivering great outcomes for our members, and that’s becoming even more important as the sector continues to evolve. Signing the Skills Compact reflects our ongoing commitment to investing in our colleagues to help them build the capabilities they’ll need for the future, including AI, while creating opportunities for others to join and grow their careers with us. By continuing to invest in learning, development and inclusive career pathways, we’re ensuring our colleagues are equipped to meet the changing needs of our members and of the communities we serve.”
Nathan Adams, Chief People Officer, Lloyd’s of London: “Lloyd’s is proud to be working with industry partners to address fundamental UK skills gaps and strengthen the long-term competitiveness of both Lloyd’s and the financial services sector. This reflects our ambition to be an organisation where capability keeps pace with ambition, through sustained investment in skills, leadership, data and technology.”
Sharon Doherty, Chief People and Places Officer, Lloyds Banking Group: “Building the critical skills, confidence and adaptability needed to thrive in a changing workplace will be essential if the UK is to capture the growth opportunities presented by AI and other emerging technologies. Working together across industry and government will be key to achieving this. At Lloyds, we’re focused on helping colleagues develop the skills they need to succeed in the jobs of the future.”
Maria Kokkinou, Chief People Officer, NatWest Group: “Helping people build confidence, develop new skills and access the right opportunities is essential to building the talent and skills our industry needs for the future and supporting the wider economy. We are proud to be an early signatory and supporter of the Financial Services Skills Compact and are fully behind its ambition to close skills gaps. Alongside investing in our own colleagues, we’re committed to supporting the development of new talent to ensure the UK has the skills it needs to stay competitive as the nature of work and the way our industry serves customers rapidly changes.”
Orlagh Hunt, Chief People Officer, OSB Group: “OSB Group is delighted to become a signatory of the Financial Services Skills Commission’s Skills Compact. We are committed to supporting our colleagues thrive and become future-fit in an evolving skills landscape. As skills becomes the most important currency for our organisations, it’s important for the Financial Services industry to share, collaborate and invest collectively to the skills in our market so we can sustain a strong future for our economy together. We greatly value the work that the Commission does to steward us through the skills agenda.”
Andrea Knott, Chief People Officer, Paragon Banking Group: “The future of financial services depends on the skills we build today. At Paragon, we’re committed to helping our colleagues develop the capabilities they need to succeed in a rapidly changing environment, while creating opportunities for the next generation of talent. That’s why we’re proud to support the Financial Services Skills Compact. By working together across the sector, we can strengthen skills, widen access to opportunity, and ensure our industry has the talent and capability it needs for the future.”
Stephanie Ashmore, Global Head of Talent, Inclusion and Employee Experience, Schroders: “Becoming a signatory of the Financial Services Skills Compact reinforces Schroders’ commitment to investing in lifelong learning, strengthening talent pipelines and working with others across the sector to close the skills gaps that will shape our future. Our people give us our active edge in terms of delivering relevant and innovative investment solutions which meet the evolving needs of our clients.”
Will Brown, Group Head of Human Resources, Standard Chartered: “At Standard Chartered, we see skills as the foundation of a resilient and productive workforce. The Financial Services Skills Compact reflects the importance of collective action to build the capabilities our sector needs, and we are proud to support it as we continue to invest in reskilling, mobility and future-ready careers.”
Sara Thompson, Chief People Officer, Standard Life: “The financial services sector is vital to the UK economy, and ensuring our workforce is future-ready is essential to driving growth. In partnership with Government, employers have a key role to play in helping people develop the skills they need to succeed in a changing workplace. We’re delighted that our employees will benefit from the Financial Services Skills Compact. As a pensions specialist, we know better retirements are shaped long before people stop working. Helping people build skills, adapt to change and strengthen their financial resilience is part of creating a world worth retiring into. We welcome the Compact’s focus on practical action and accountability and look forward to working with government and industry to drive positive change and improve financial wellbeing.”
Luke McClaran, Group Chief People Office, Vitality: “At Vitality, we see skills as the foundation of a healthier, more resilient sector. That’s why we’re proud to back the Financial Services Skills Compact and its work closing gaps across the industry. We believe technology should free people up, not leave them behind. Which is why we’re focused on helping our own employees build skills for not only today but the future too and creating clear paths for new talent to join us. Working together with others in the sector, we can build a workforce that supports growth, innovation, productivity and long-term competitiveness.”
Holly Rankin, Chief People Officer, Yorkshire Building Society: “We’re proud to support the Financial Services Skills Compact and the shared ambition to help people develop the capabilities they need for the future. At Yorkshire Building Society, we’re already investing in skills development and learning opportunities for colleagues, and signing the Compact reinforces our commitment to continuing that journey.”
Iain Kendrick, Chief People Officer at Zopa, said: “The Skills Compact is an opportunity for employers to shape the next phase of key skills in a time of significant change. No single financial services business can close the UK’s skills gap alone, but together we can create clearer pathways into employment, better align learning with the capabilities employers need, and help more people thrive in a rapidly changing economy. At Zopa, we’re proud to play our part in that collective effort — from supporting industry-led upskilling initiatives such as Jobs2030.ai to contributing to one of the most ambitious workforce development frameworks through the Skills Compact.”
Nick Bartlett, Chief Executive, CFA UK: “When engaging with CFA UK members and the investment profession, we continually hear of the impact and challenges developments such as AI are having on workflows and jobs, and the desire from practitioners to upskill. We have a huge amount of investment talent within the UK. We recognise and fully support the importance of this initiative in seeking to close the skills gap and develop a more competitive and resilient UK financial services sector.”
Tanya Retter, Chief Executive at the Chartered Banker Institute: “The Chartered Banker Institute is delighted to support the Financial Services Skills Compact and to stand alongside organisations across the sector in committing to invest in their people and future talent. As the professional body for banking, we believe that professionalism, ethical conduct and continuous professional development are fundamental to building and maintaining public trust in financial services. As technology, regulation and customer expectations continue to evolve, it is essential that colleagues at every stage of their careers have access to high-quality learning and development opportunities that enable them to adapt, grow and contribute with confidence. The Compact provides an important framework for collective action, helping to strengthen skills, support innovation and foster a culture of lifelong learning across the sector. By investing in people and professional capability, we can help ensure that financial services remains trusted, resilient and equipped for the opportunities and challenges ahead.”
Matthew Hill, Chief Executive of the Chartered Insurance Institute: “Insurance, long-term savings and financial planning support more than 300,000 jobs across the UK, and the sector’s future strength depends on the skills and professionalism of its people. The Chartered Insurance Institute is proud to support the Skills Compact, which recognises that building a strong future workforce is a shared responsibility. By opening clearer routes into financial services and supporting ongoing development, we can help ensure that insurance and financial planning professionals continue to deliver the highest standards of service to individuals, firms and wider society.”
Mandy Gill, Executive Director of Learning, Chartered Institute for Securities & Investment: “As part of the HMT Steering Group, we welcome the opportunity to support the Financial Services Skills Compact on behalf of our members, stakeholders and the future talent coming through, who are critical to the lifeblood of our profession.
“Our sector is undergoing immense change, with AI at the forefront and customer confidence being central to the equation. Technological change in particular needs to go hand in hand with trust, with ethical frameworks being integral to both AI development and to our profession-wide skills and training. People are at the forefront of the skills evolution and the Compact demonstrates the profession’s collective commitment.
”The Financial Services Skills Compact is a testament to the power of joined up thinking between government, professional bodies and business and we look forward to supporting our members across the UK regions in upskilling and reskilling their people.”
Chris Hayward, Policy Chairman, City of London Corporation: “We are proud to support the Financial Services Skills Compact, developed by the Financial Services Skills Commission. A highly skilled workforce is essential to maintaining the UK’s position as a leading global financial centre, particularly as AI, digital innovation and changing workforce needs reshape our industry. By bringing together government and industry to invest in people, strengthen talent pipelines and address critical skills gaps, the Compact represents an important commitment to ensuring the UK’s remains the world’s leading destination for financial services.”
Michael Crowe, Chief Executive Officer, Finance Isle of Man: “The financial services sector is facing a period of significant change and opportunity, making investment in skills and talent more important than ever. Ensuring our workforce has access to the right development opportunities will be critical to sustaining growth, driving innovation and maintaining the Isle of Man’s reputation as a leading international finance centre. We welcome initiatives that encourage employers to invest in upskilling and reskilling, attract new talent into the sector and promote a culture of continuous learning. Building a highly skilled and adaptable workforce is essential to meeting the evolving needs of the industry and supporting long-term economic success.”
Caroline Wagstaff, Chief Executive Officer, London Market Group: “We completely support the Skills Compact because talent is probably the single most important issue for the London insurance market. As a profession which has people at its heart, the flow of young talent and the continual upskilling of professionals at every stage will keep this world-leading industry in vibrant health.”
Miles Celic OBE, Chief Executive Officer, TheCityUK: “The UK’s strength as a world-leading financial centre depends on the skills, adaptability and ambition of its people. As AI and new technologies transform our industry, investing in talent is not optional but central to competitiveness, innovation and growth. The Financial Services Skills Compact is a welcome and practical step towards closing skills gaps, widening routes into the sector and ensuring financial and related professional services continue to create high-quality jobs and support growth across the UK.”
Sandy Begbie CBE, Chief Executive Officer, Scottish Financial Enterprise: “As we set out in our recent Skills Action Plan, SFE understands the scale and importance of the skills challenge facing our industry. Developments in data and AI are changing the way we work, as well as the skills needed for both individuals and businesses to thrive. That is why we are pleased to support the Financial Services Skills Commission’s Skills Compact and to highlight the importance of skills needed for our sector to remain competitive and to drive growth.”